No—an old roof does not automatically mean your Florida homeowners insurer can drop you solely because of its age. Florida law protects roofs less than 15 years old from age-only refusal to issue or renew coverage and gives owners of older roofs an inspection route when at least 5 years of useful life remain. Those protections do not erase roof-condition problems, other underwriting grounds, or deadlines in an insurer’s notice.
- Will my insurance drop me if my roof is too old in Florida? Age alone does not automatically justify nonrenewal.
- Florida Statutes section 627.7011 protects roofs under 15 years old against age-only refusal to issue or renew homeowners coverage.
- Roofs at least 15 years old have an inspection route when at least 5 years of useful life remain.
- Roofsmartflorida provides Southwest Florida roofing services; your insurer decides coverage, not your roofing contractor.
Will my insurance drop me if my roof is too old in Florida?
Not solely because your roof reaches a particular birthday. For a 2026 homeowners insurance review, Florida Statutes section 627.7011(5) is the key roof-age provision. It addresses refusal to issue or renew a homeowners policy solely because of roof age, rather than guaranteeing coverage regardless of condition.
Start with the insurer’s written reason, not a replacement estimate. This guide to preparing your roof for a home insurance renewal inspection explains the preparation side.
| Roof situation | What the roof-age provision means | Best next move | Limitation |
|---|---|---|---|
| Roof less than 15 years old | An insurer cannot refuse to issue or renew solely because of age | Document installation age and ask for the specific underwriting concern | Condition and other underwriting grounds still matter |
| Roof at least 15 years old | You must be allowed an inspection at your expense before replacement is required under this provision | Arrange an inspection by an inspector authorized under the statute | Age alone does not establish remaining useful life |
| Older roof with at least 5 years of useful life documented | The insurer cannot refuse to issue or renew solely because of roof age | Submit the report and request a written underwriting response | The report is not a guarantee of coverage on other grounds |
| Roof with documented defects | Roof-age protection does not resolve the defects | Get a written repair or replacement assessment | Completing work does not itself confirm renewal |
These rules concern homeowners insurance. Do not assume the same roof-age protection applies to a commercial building policy, condominium association policy, or every specialized property policy.
Why this matters
Replacing a roof and preserving insurance are related decisions, but they are not the same decision. A replacement contract does not reverse a nonrenewal notice, and a useful-life report does not repair a leak.
For your 2026 renewal, you need two clear answers: what the insurer requires and what the roof actually needs. Get both in writing before committing to replacement solely to satisfy an age concern.
Roofs under 15 years old: age alone is not enough
Florida’s roof-age provision prohibits an insurer from refusing to issue or renew a homeowners policy solely because a roof is less than 15 years old. That is an age-based protection, not a blanket statement that every younger roof is acceptable.
If the insurer identifies missing roofing, active leakage, deterioration, or another condition issue, address that stated concern directly. Telling the insurer that the roof is younger than the threshold does not answer evidence of damage.
Find the installation permit, final inspection record, invoice, or other reliable documentation. Check that the record concerns the roof covering, not an unrelated repair. If the insurer’s roof age is wrong, submit the supporting documents and ask for correction.
Best for: homeowners whose renewal concern rests on an incorrect installation date or an age-only explanation. The benefit is a documented basis for reconsideration; the limitation is that age records cannot establish present condition.
Roofs at least 15 years old: inspection comes before an age-based replacement demand
For a roof at least 15 years old, section 627.7011(5) requires an opportunity for an inspection at the homeowner’s expense before requiring replacement under the roof-age provision. An authorized inspector’s finding of at least 5 years of remaining useful life protects against refusal to issue or renew solely because of roof age.
This is not an automatic extension. The inspector must evaluate the actual roof, and you must submit the resulting documentation through the insurer’s process.
Ask the insurer which report format, photographs, credentials, and submission method it requires. Then confirm that the person performing the inspection qualifies under the statute. A general sales proposal is not a substitute for a useful-life inspection report.
Best for: homeowners with an older roof whose condition supports continued service. The benefit is evidence against an age-only replacement demand; the limitation is that an inspection can also document defects requiring attention.
Why insurance decisions about older roofs vary
The statutory age thresholds are only part of the decision. Your insurer’s stated grounds and your roof’s documented condition determine what you need to address.
- Age records: A verified installation date is stronger than an estimate based on the home’s age.
- Remaining useful life: The older-roof protection depends on the inspection finding, not your expectation of how long the material should last.
- Documented condition: Leaks, damaged covering, and deteriorated components require their own response.
- Policy type: The homeowners provision is not a universal rule for all property insurance.
- Notice wording: An age-only objection differs from a notice identifying specific defects or other underwriting grounds.
- Report quality: An unsigned estimate or incomplete photo package does not provide the same evidence as the requested inspection documentation.
A tile or metal roof’s general reputation for longevity does not prove your roof’s remaining useful life. The assessment must concern your installed roof, including components that are not visible from the street.
What should I do after receiving a roof-related insurance notice?
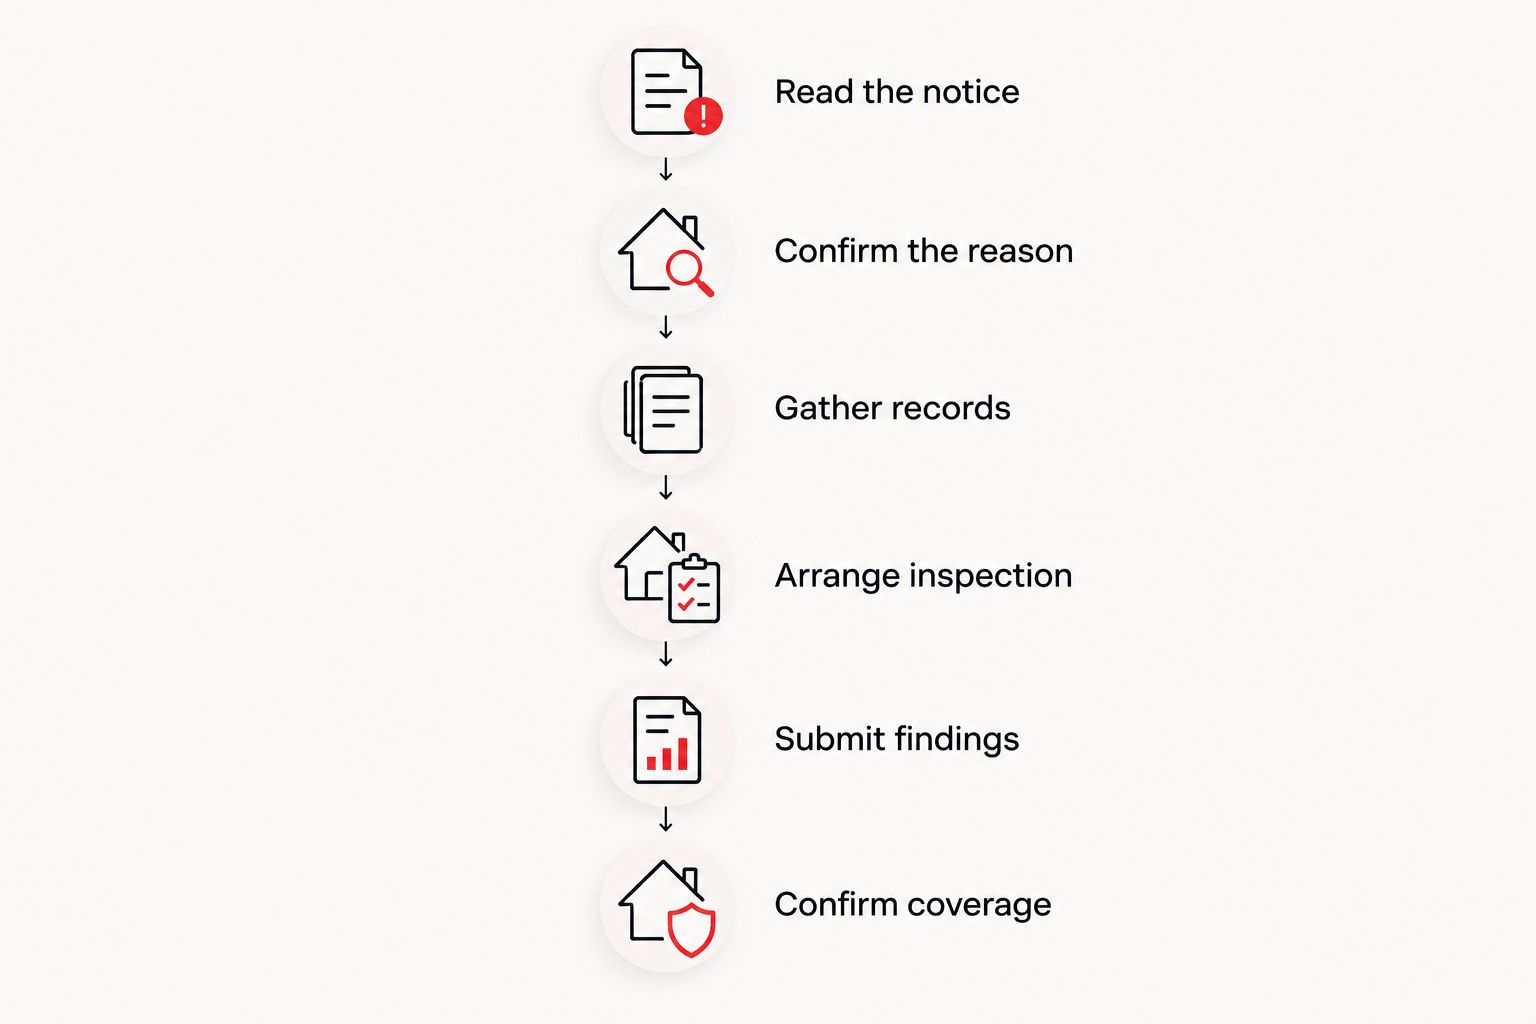
Treat the notice as a deadline-driven document, not a suggestion. Follow this sequence for a 2026 roof-related renewal review, while continuing to address urgent damage safely.
- Read the notice. Identify whether it concerns cancellation, nonrenewal, a request for information, or required corrective work. Record the effective date and response deadline exactly as written.
- Confirm the reason. Ask whether the concern is roof age alone, roof condition, missing documentation, or another underwriting issue. Request the answer in writing.
- Gather records. Collect installation documents, previous inspection reports, repair invoices, and dated photographs. Keep copies of everything submitted.
- Arrange inspection. Confirm the inspector’s qualifications and the required report before scheduling. Ask for findings on condition and remaining useful life, not just a replacement proposal.
- Submit findings. Use the insurer’s requested channel and obtain confirmation of receipt. Ask whether additional documentation or work remains outstanding.
- Confirm coverage. Obtain the insurer’s written decision. If the issue remains unresolved, discuss replacement coverage with a licensed insurance agent before the existing policy ends.
Do not assume a scheduled inspection, repair appointment, or complaint pauses the notice. Ask the insurer directly whether it has changed or withdrawn the stated deadline.
Do I need a roof inspection, repairs, or full replacement?
Choose the next step from documented findings, not roof age alone. An inspection answers a condition question; repairs address defined defects; replacement addresses a roof that needs broader renewal.
| Option | Best for | Benefit | Limitation |
|---|---|---|---|
| Useful-life inspection | An older roof facing an age-based objection | Documents condition and remaining useful life | Does not fix defects or guarantee renewal |
| Targeted repair | A roof with repairable, localized problems | Addresses the identified damage | Does not establish the condition of every roof component |
| Roof replacement | A roof whose documented condition calls for replacement | Replaces the roofing within the agreed scope | Does not automatically resolve unrelated insurance issues |
Ask the contractor to separate observed defects from recommended work. You need to understand whether replacement follows from widespread deterioration, a particular roof-system problem, or an insurer’s stated requirement.
Roofsmartflorida roofing services are best suited to Southwest Florida homeowners who need repair or replacement work evaluated separately from their insurer’s coverage decision. The company provides residential and commercial roofing installation, repair, and replacement across Cape Coral, Fort Myers, Naples, and surrounding Southwest Florida counties.
Roofsmartflorida can address roofing work, but it cannot guarantee an insurer’s renewal decision. Keep the contractor’s scope of work and the insurer’s written requirements together so neither gets mistaken for the other.
Discuss your roof’s next step
Roofsmartflorida provides roof repair and replacement services across Southwest Florida.
Can my insurer cancel me before my renewal date?
The 15-year and 5-year rules do not answer every midterm cancellation question. Cancellation ends coverage before the policy’s scheduled expiration; nonrenewal means the insurer will not continue the policy after its term ends.
Ask a licensed insurance agent to review the actual notice, policy, timing, and stated grounds. Florida’s Department of Financial Services can also assist consumers with insurance questions and complaints. Do not treat a general roof-age explanation as a ruling on a specific cancellation notice.
Does a roof inspection guarantee another 5 years of coverage?
At least 5 years of remaining useful life is not a promise of 5 years of insurance. It is the useful-life finding tied to the older-roof age protection in the homeowners statute.
The insurer still evaluates other applicable underwriting grounds, and future roof damage changes the facts. Keep the report, but continue maintaining the roof and responding to policy notices.
Will insurance pay to replace an old roof?
The 15-year roof-age threshold concerns eligibility for homeowners coverage, not whether an insurer owes you a replacement. A roof-related renewal demand is not the same as an accepted insurance claim.
Claim payment depends on the policy, cause of damage, exclusions, deductible, and settlement terms. For your 2026 decision, separate maintenance or replacement planning from any claim involving a specific loss.
FAQ
Will my insurance drop me if my roof is too old in Florida?
Roof age alone does not automatically justify refusal to issue or renew Florida homeowners insurance. Section 627.7011(5) protects roofs under 15 years old and provides an inspection route for older roofs with at least 5 years of useful life remaining.
Does Florida require a new roof every 15 years for insurance?
No, Florida does not impose a universal requirement to replace a roof every 15 years for homeowners insurance. Older roofs have an inspection route under the roof-age provision, while condition and other underwriting grounds still matter.
Who pays for the inspection on an older roof?
The homeowner pays for the inspection described in Florida’s older-roof provision. Confirm the inspector’s statutory qualifications and the insurer’s documentation requirements before arranging it.
Is a four-point inspection the same as a useful-life roof report?
A four-point inspection is not automatically interchangeable with the roof report your insurer requests. It addresses roofing, electrical, plumbing, and heating or cooling systems; confirm whether its roof section supplies the required findings and credentials.
Does wind mitigation prove my roof has enough life left?
A wind mitigation inspection does not automatically establish sufficient remaining useful life. Wind-resistance features and roof condition answer different questions, so ask which documentation the insurer needs.
Can I ignore a nonrenewal notice while disputing the roof age?
No, do not ignore a nonrenewal notice while disputing roof age. Submit your evidence, track the stated deadline, and request written confirmation of any change to the insurer’s decision.
Does replacing my roof guarantee my insurer will renew?
Roof replacement does not guarantee renewal. Ask whether the insurer has other outstanding requirements and obtain its written coverage decision after submitting completion documents.
One last thing
A roof can stop leaking and still need insurance documentation; it can also qualify for age protection and still need repairs. Those are separate checks, and completing one does not complete the other.
Before closing your 2026 roof file, save the final report, work records, submission receipt, and insurer’s response together. Your strongest next move is not assuming the issue is resolved—it is obtaining a written answer that says what happens to your policy.