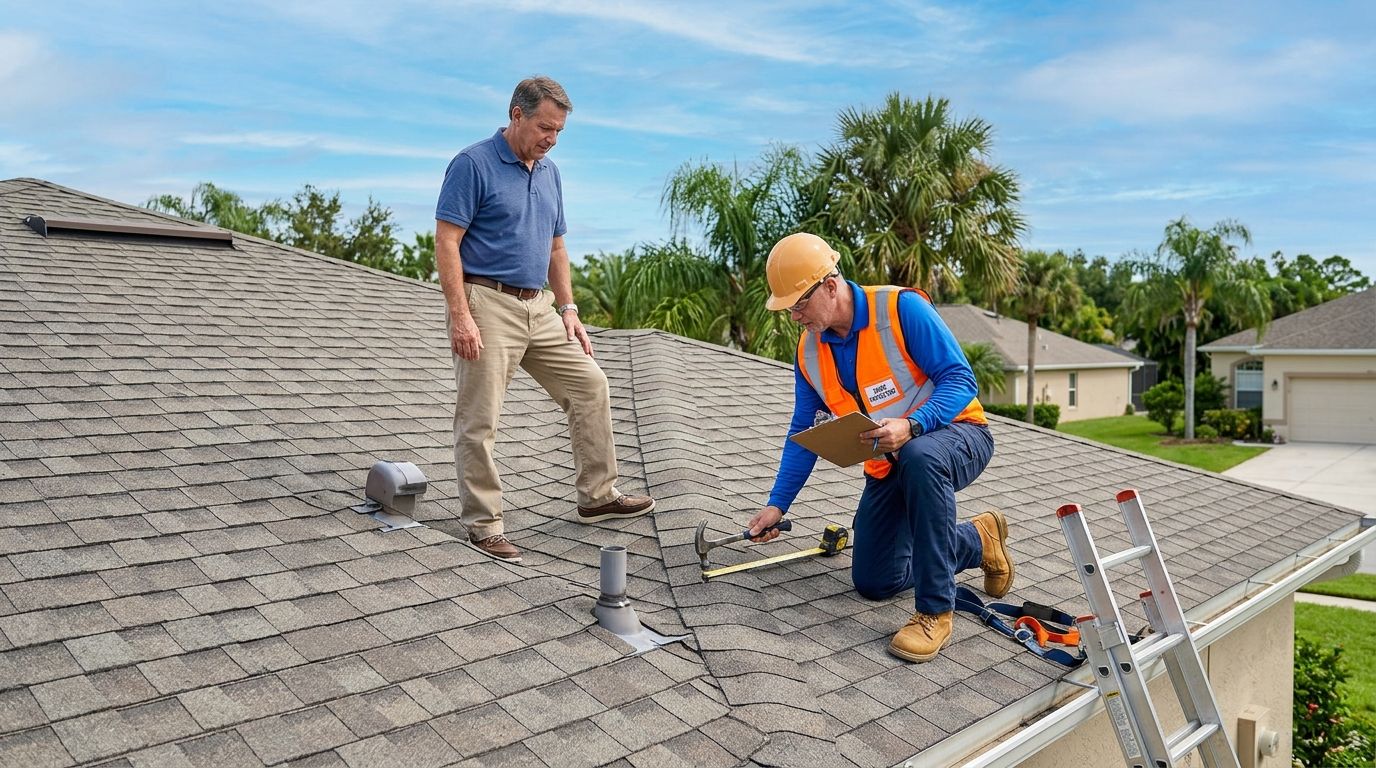
A roof inspection for insurance renewal in Florida checks the same things a claims adjuster looks for after a storm: the age and condition of the roof covering, visible damage or wear, flashing and vent boots, and whether the home has recorded wind mitigation features. Clear the roof and gutters, photograph every elevation, and repair loose or missing shingles/tiles before the inspector's visit — insurers in 2026 are rejecting or non-renewing policies over cosmetic issues that would have passed five years ago. The hidden cost most homeowners miss: a roof over 15-20 years old can trigger a mandatory 4-point inspection even when nothing looks wrong from the ground.
- Clear debris and photograph the roof before a roof inspection for insurance renewal Florida carriers require in 2026.
- Roofs 15-20+ years old typically need a 4-point inspection, not just a visual check.
- A wind mitigation inspection can lower premiums but only if features are documented correctly.
- Roof Smart of SW Florida handles 4-point and wind mitigation inspections across Cape Coral, Fort Myers, and Naples.
- Unrepaired minor damage is the single most common reason Florida carriers non-renew a policy.
Why this matters
Florida's property insurance market has been tightening every renewal cycle since 2022, and 2026 is no exception. Carriers now send third-party inspectors or request updated 4-point and wind mitigation forms at renewal, not just at binding.
A roof that looks fine to you can still fail an insurer's checklist over granule loss, lifted tile, or a missing permit record. Homeowners who prep ahead of the visit avoid the two outcomes that cost the most: a non-renewal notice or a policy rewritten with a higher deductible on the roof.
What does a roof inspection for insurance renewal in Florida check?
Most Florida carriers, or the third-party inspection companies they hire, walk through the same checklist during a renewal visit:
- Roof age and material — the effective age matters more than the install date if repairs have been logged.
- Surface condition — cracked tile, curled or missing shingles, exposed underlayment, and rusted metal panels.
- Flashing and penetrations — vent boots, skylights, and chimney flashing are common leak points inspectors flag.
- Gutters and drainage — clogged or detached gutters signal deferred maintenance to an underwriter.
- Wind mitigation features — roof-to-wall connections, secondary water barrier, and opening protection, all of which affect premium.
- Prior repairs and permits — patched sections without permits raise questions about workmanship.
Walking your own roof (or hiring someone to) against this list before the carrier's inspector shows up is the fastest way to catch what would otherwise cost you at renewal. A 4-point roof inspection covers roofing, electrical, plumbing, and HVAC, and it's the document most Florida carriers request once a home passes the 15-20 year mark.
4-point inspection: what it covers for insurance renewal
A 4-point inspection is narrower than a full home inspection — it exists specifically to give an underwriter a snapshot of the roof, electrical panel, plumbing, and HVAC system's remaining useful life. For the roof section, the inspector documents the covering type, approximate age, and any visible deterioration, then photographs problem areas.
Best for: homes over 15 years old renewing a policy or switching carriers in 2026. Verdict: Buy the inspection proactively rather than waiting for the carrier to demand one on their timeline — a proactive report gives you time to fix issues before the renewal deadline instead of scrambling against a non-renewal notice.
Wind mitigation inspection: what it covers for insurance discounts
A wind mitigation inspection documents features that reduce storm damage risk: roof shape, roof-to-wall attachment type, roof deck attachment, secondary water resistance barrier, and opening protection like impact windows or shutters. Florida law requires carriers to offer a premium credit for verified features, but the discount only applies if the form is filed correctly and matches what's actually on the house.
Best for: any Florida homeowner who hasn't updated their wind mitigation inspection for a homeowners insurance discount in the last 3-5 years, especially after a roof replacement. Verdict: Buy — the inspection itself typically costs far less than the annual premium credit it can unlock over multiple renewal cycles.
Roof inspection type comparison
| Inspection type | Purpose at renewal | Who typically needs it |
|---|---|---|
| 4-point inspection | Confirms roof/electrical/plumbing/HVAC condition | Homes 15-20+ years old |
| Wind mitigation inspection | Documents storm-resistant features for discounts | Any homeowner seeking a premium credit |
| General roof inspection | Baseline condition check, no insurance form | Homeowners doing routine maintenance |
Why insurance renewal outcomes vary
A handful of factors decide whether your Florida renewal goes smoothly or triggers a non-renewal letter:
- Roof age — carriers apply stricter scrutiny past the 15-20 year mark regardless of visible condition.
- Missing or expired wind mitigation form — no current form means no discount, and some carriers treat it as a red flag.
- Unpermitted prior repairs — patched areas without a permit on file raise underwriting questions.
- Coastal exposure — proximity to the coast in Naples, Bonita Springs, or Fort Myers affects both premium and inspection frequency.
- Claims history — a recent roof claim increases the odds of a follow-up inspection at renewal.
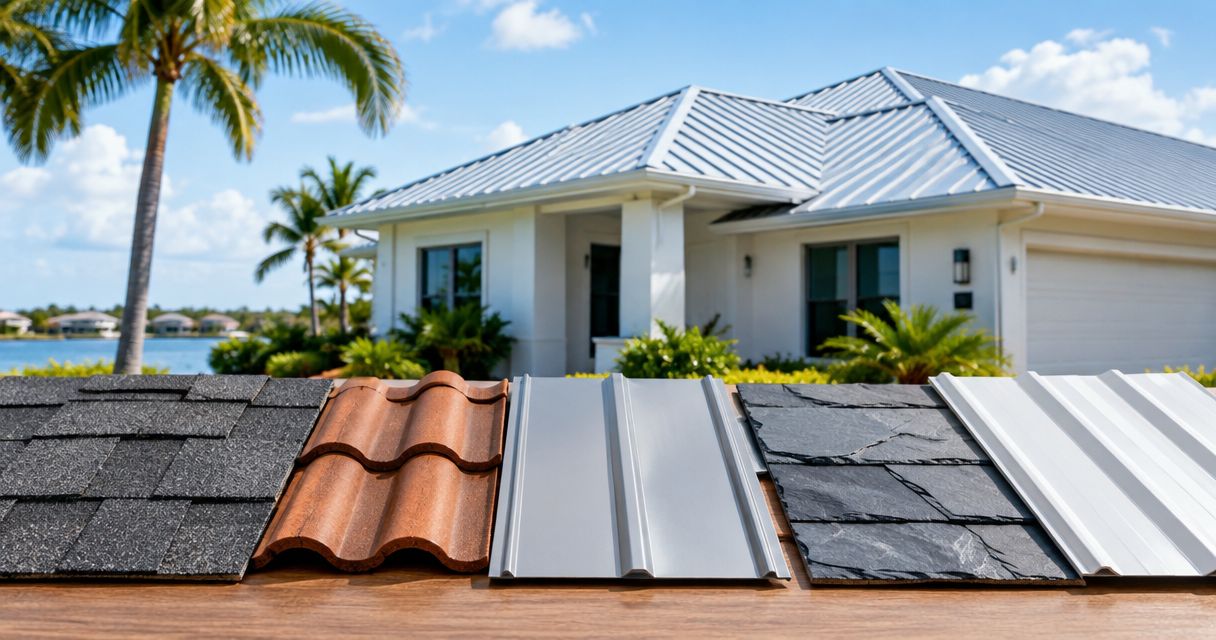
- Material type — tile and metal roofs tend to score better on wind mitigation forms than aging shingle roofs.
How often do Florida insurers require a roof inspection for renewal?
Most Florida carriers request a fresh inspection every 3-5 years, or immediately after a roof is 15-20 years old, whichever comes first. Some carriers also trigger a re-inspection after any reported storm damage in the area, even if your home wasn't directly hit.
Does roof age affect insurance renewal in Florida?
Roof age is one of the biggest single factors in a Florida renewal decision, and roofs past 15-20 years often require a passed 4-point inspection just to keep the policy in force. Newer roofs, even on older homes, generally clear renewal review faster because the material hasn't started showing wear.
What happens if my roof fails the insurance inspection?
A failed inspection usually means the carrier issues a non-renewal notice or requires repairs within a set window, often 30-60 days, before the policy renews. Homeowners who complete the repairs and resubmit documentation on time typically keep their existing coverage instead of being forced into the surplus lines market.
“A proactive 4-point inspection buys you time to fix problems before a carrier's deadline forces the issue.”
If your last inspection turned up issues, or you're not sure what shape your roof is in before the renewal date, Roof Smart of SW Florida runs both 4-point and wind mitigation inspections across Cape Coral, Fort Myers, and Naples and documents findings the way carriers expect to see them.
Get your roof renewal-ready
Free, no-pressure evaluation before your inspection date.
FAQ
How much does a roof inspection for insurance renewal cost in Florida?
Cost varies by inspector and roof size, and the figure isn't fixed across Southwest Florida markets, so ask for a quote at the time of scheduling. Budget for it as a small line item against the premium savings or repair costs it can prevent.
Is a 4-point inspection the same as a wind mitigation inspection?
No, a 4-point inspection covers roof, electrical, plumbing, and HVAC condition, while a wind mitigation inspection documents storm-resistant construction features for a premium discount. Many Florida homeowners need both at renewal, especially past the 15-20 year roof age mark.
How long is a 4-point inspection valid for insurance purposes?
Most Florida carriers accept a 4-point inspection for one renewal cycle, generally 1-2 years, before requiring an updated report. Check with your specific carrier since some request refreshed forms more often after a claim.
Can I get a homeowners insurance discount for a new roof in Florida?
Yes, a new roof paired with a current wind mitigation inspection can qualify for a premium credit under Florida's mandated discount structure. The discount only applies once the form documenting the roof-to-wall connection and other features is on file with the carrier.
What roof age triggers a mandatory insurance inspection in Florida?
Roofs around 15-20 years old are the point at which most Florida carriers require a 4-point inspection before renewing coverage. Some carriers set the threshold earlier depending on the roofing material and coastal location.
Will insurance drop me if my roof fails inspection?
A failed inspection can lead to a non-renewal notice, but most carriers give a repair window, often 30-60 days, before making that decision final. Completing repairs and resubmitting documentation promptly is usually enough to keep the existing policy.
One last thing
The detail homeowners skip most often: photographing the roof from all four elevations before the inspector arrives, dated and time-stamped. If a dispute comes up later about pre-existing damage versus what happened during the inspection window, those photos are the only record you'll have, and in 2026's tighter Florida market, that record can be the difference between a smooth renewal and a fight with the carrier.