Wind mitigation inspection in LaBelle checks specific hurricane-resistant features on your roof and home structure so your insurance carrier can apply mitigation credits to your premium. LaBelle sits inland in Hendry County, away from the coastal wind zones that drive Naples or Fort Myers rates, but Florida's statewide wind mitigation credit system still applies to every insured home in the state. The inspection itself is short, the paperwork determines real dollars on your renewal, and most LaBelle homeowners have never had one done.
- A wind mitigation inspection labelle homeowners book takes under an hour and can lower premiums for years.
- The OIR-B1-1802 form is the only document Florida insurers accept as proof of mitigation features.
- Roof Smart of SW Florida completes wind mitigation inspections across Hendry County alongside roof repair and replacement work.
- Skipping the inspection after a 2026 roof replacement means paying full premium for features you already installed.
Why wind mitigation inspection matters for LaBelle homeowners
LaBelle's housing stock runs older than the coastal cities to the west, and older homes tend to lack the hip roofs, secondary water barriers, and reinforced roof-to-wall connections that trigger the biggest insurance credits. That gap is exactly what a wind mitigation inspection documents.
Insurers in Florida are required by state law to offer premium discounts for verified wind-resistant construction, but the discount only applies once the OIR-B1-1802 form is on file. No form, no credit, regardless of what's actually built into the roof.
Homeowners who replaced a roof in 2026, added hurricane straps, or upgraded to impact-rated shingles are often still paying pre-upgrade premiums simply because nobody filed the paperwork. A wind mitigation inspection is the only way to convert a roof upgrade into a rate reduction.
How to get a wind mitigation inspection done right
Confirm what your current roof and home already qualify for
Before booking anything, walk the property and note what you can verify without a ladder.
- Roof shape (hip roofs score higher than gable roofs)
- Approximate roof age and any permit paperwork from past work
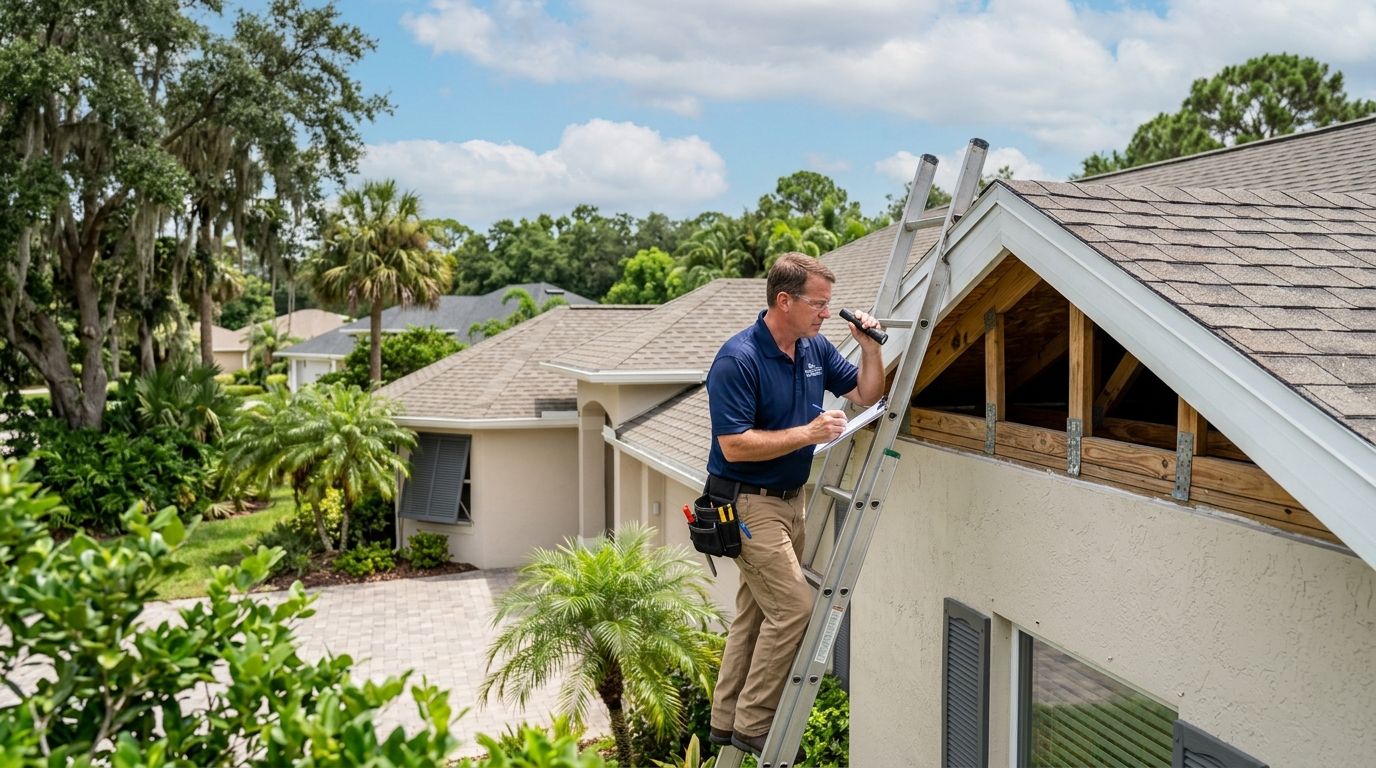
- Visible roof-to-wall connections in the attic (clips vs. straps vs. nothing)
- Presence of a secondary water barrier or peel-and-stick underlayment
- Impact-rated or laminated glass on windows and doors
- Opening protection like shutters or reinforced garage doors
Pull your permit history first
Hendry County's building department keeps permit records that can shortcut the inspection.
- Request the permit card for your most recent roof replacement
- Check the permit date against Florida Building Code adoption years, since code changes affect what qualifies
- Look for a final inspection sign-off, not just a permit application
- Save any manufacturer certification for roof-to-wall connectors if the installer provided one
Schedule the inspection with a licensed inspector
Florida requires the inspection to be performed by a licensed contractor, home inspector, engineer, or certain building officials — not a random measuring service.
- Confirm the inspector's license number before booking
- Ask whether the inspection covers the full roof, attic, and openings or just a partial check
- Get a written estimate of what's included before the appointment
- Ask if photos are included with the report, since some carriers request them
Prepare the property before the inspector arrives
A blocked attic hatch or locked gate turns a 45-minute visit into a rescheduled one.
- Clear access to the attic hatch
- Unlock gates, sheds, or side entries the inspector needs
- Have your most recent permit or roof invoice ready to hand over
- Remove furniture or storage blocking window and door openings
The inspection itself takes under an hour in most cases, since the inspector is documenting existing conditions, not testing anything. Homeowners who want the roof-specific parts of that inspection handled by the same crew that did the work can pair it with a roof inspection service visit, which checks the same roof-to-wall and underlayment details from a roofing perspective before the wind mitigation paperwork goes in.
Understand what's actually on the OIR-B1-1802 form
The form has seven sections, and each one maps to a specific credit category on your policy.
- Building code year — determines the baseline wind rating your home was built to
- Roof covering — age and type of shingles, tile, or metal
- Roof deck attachment — nail pattern and spacing on the roof deck
- Roof-to-wall attachment — clips, straps, or toe-nails
- Roof geometry — hip vs. gable vs. other shapes
- Secondary water resistance — presence of a sealed roof deck barrier
- Opening protection — shutters, impact glass, or garage door reinforcement
Missing even one section weakens the credit. The form is only as good as the detail the inspector records, which is why a rushed inspection often costs homeowners money they never realize they lost.
Submit the report to your insurance carrier the right way
Getting the form doesn't automatically change your premium.
- Send the signed OIR-B1-1802 form directly to your agent, not just your carrier's general email
- Ask for written confirmation the discount was applied
- Request the effective date of the new premium in writing
- Keep a copy of the form for the life of the policy, since carriers can request it again
Homeowners who want to see exactly how these credits translate into savings before scheduling anything can review wind mitigation inspection for homeowners insurance discounts for a breakdown of which features carry the most weight.
Fix the gaps the inspection uncovers
An inspection that reveals missing roof-to-wall clips or a deteriorated roof isn't a dead end — it's a punch list.
- Compare the inspector's findings against your carrier's discount table
- Prioritize roof-to-wall retrofits, since they're often the cheapest fix relative to the credit earned
- Re-inspect after any qualifying repair or replacement to lock in the new credit
- Ask a licensed roofer whether a partial upgrade (like adding a secondary water barrier during re-roofing) makes financial sense before your next renewal
Book a wind mitigation inspection in LaBelle
Roof Smart of SW Florida inspects roofs and files the paperwork insurers require.
Comparison: who should do your wind mitigation inspection
| Option | Best for | Key limitation |
|---|---|---|
| Independent wind mitigation inspector | Homeowners who just want the OIR-B1-1802 form filed | Doesn't catch roofing problems that aren't credit-related |
| Licensed roofing contractor | Homeowners planning repairs or replacement anyway | Contractor must hold the right license type to sign the form |
| Home inspector (general) | Homeowners bundling with a broader home inspection | Roof-specific detail can be thinner than a roofer's report |
| Carrier-ordered inspection | Homeowners renewing a policy that requires it | Carrier picks the inspector, not you, and timing is out of your control |
Verdict: pairing the wind mitigation inspection with a licensed roofing contractor already on your property for repair or replacement work is the most efficient route for LaBelle homeowners, since one visit covers both the roof condition and the credit paperwork.
Common mistakes LaBelle homeowners make
- Assuming an older inland home won't qualify for anything. Even a home with no upgrades usually qualifies for some credit once roof shape and building code year are documented — skipping the inspection guarantees zero credit rather than a small one.
- Filing the form and never confirming the premium changed. Agents don't always apply discounts automatically; homeowners who don't follow up in writing sometimes wait a full renewal cycle for nothing.
- Waiting until a claim to find out the roof doesn't qualify. Wind mitigation credits and claim eligibility are separate systems, but homeowners often discover roof deficiencies only after storm damage, when it's too late to plan the fix.
- Using an inspection older than five years for a new policy. Many carriers want a current report, and an outdated 2019 or 2020 inspection can be rejected outright in 2026.
- Not re-inspecting after a roof replacement. A brand-new roof with a hip shape and sealed deck earns nothing on the policy until a fresh inspection documents it.
FAQ
How much does a wind mitigation inspection cost in LaBelle?
Cost varies by inspector and property size, so confirm current pricing directly with the company you book. Ask whether the quote includes the signed OIR-B1-1802 form or just the site visit.
How long does a wind mitigation inspection take?
Most inspections take under an hour since the inspector is documenting existing conditions rather than performing repairs. Access to the attic and any locked areas speeds the visit along.
Does a wind mitigation inspection expire?
The report itself doesn't have a state-mandated expiration, but many insurance carriers request an updated inspection every five years or after a major roof change. Check with your specific carrier before assuming an old report still counts.
Can I do my own wind mitigation inspection?
No. Florida requires the inspection to be performed by a licensed contractor, engineer, home inspector, or certain building officials, and self-reported findings aren't accepted by insurers.
Will a wind mitigation inspection find roof damage too?
It can flag visible issues like a deteriorated roof deck or missing straps, but it's not a substitute for a full roof inspection focused on leaks, wear, or storm damage.
Is wind mitigation inspection worth it for an older LaBelle home?
Yes, since even homes without upgrades typically document some qualifying features like roof shape or building code year, and any documented credit beats paying full premium for features never recorded.
What form do I need for a wind mitigation discount in Florida?
The OIR-B1-1802 form is the only document Florida insurers accept as proof of wind mitigation features. It must be signed by a licensed inspector.
Should I get a wind mitigation inspection before or after a roof replacement?
After. Inspecting before replacement documents the old roof's weaker features, while inspecting after captures the new roof shape, deck attachment, and water barrier that actually earn the credit.
One last thing
The roof-to-wall attachment section of the OIR-B1-1802 form carries some of the heaviest weight in the credit calculation, and it's the one section homeowners can't verify from the ground — it requires an attic walk-through. If nobody's been in your attic since the roof went on, that's the first thing to check before assuming your home doesn't qualify for a meaningful discount in 2026.