A wind mitigation inspection insurance discount in 2026 comes down to seven graded features on your roof and openings — document them correctly and an older Southwest Florida roof can still qualify for real credits on your windstorm premium.
- A wind mitigation inspection insurance discount in 2026 hinges on roof deck, roof-to-wall, and opening protection credits.
- Cape Coral, Fort Myers, and Naples homeowners qualify differently based on roof age and construction era — book before renewal.
- Reports stay valid 5 years under Florida law, but a re-roof or new openings void the credit early.
- Roofs built before 2002 rarely pass roof-to-wall attachment credits without a retrofit — verdict: inspect first, then decide.
Why this matters
Florida law requires insurers to offer premium credits for wind-resistant construction, and the only way to prove your home qualifies in 2026 is a state-form wind mitigation inspection. Cape Coral, Fort Myers, and Naples sit in one of the highest storm-exposure corridors in the country, and insurers price that risk into every windstorm line item on your policy.
A wind mitigation inspection in Cape Coral, Fort Myers, or Naples documents roof covering, roof deck attachment, roof-to-wall connections, roof shape, secondary water barrier, and opening protection — the same categories adjusters use to calculate your discount. Roof Smart of SW Florida handles inspections across all three markets, and the same six categories show up on every report regardless of who signs it.
The report goes on the OIR-B1-1802 form, the uniform inspection form every Florida-licensed carrier has to accept. No inspection on file means no credit for 2026, regardless of how storm-ready your roof actually is.
Who this is for
This is for Southwest Florida homeowners with a windstorm renewal coming up in 2026, anyone who bought a home without a current wind mitigation report in the closing file, and homeowners who replaced their roof since their last inspection but never re-filed the paperwork. It's also for owners of homes built before 2002, when Florida's building code tightened roof-to-wall and opening standards — those roofs often qualify for fewer credits than owners assume.
What to look for in a wind mitigation inspection for insurance discounts
Roof covering and permit history
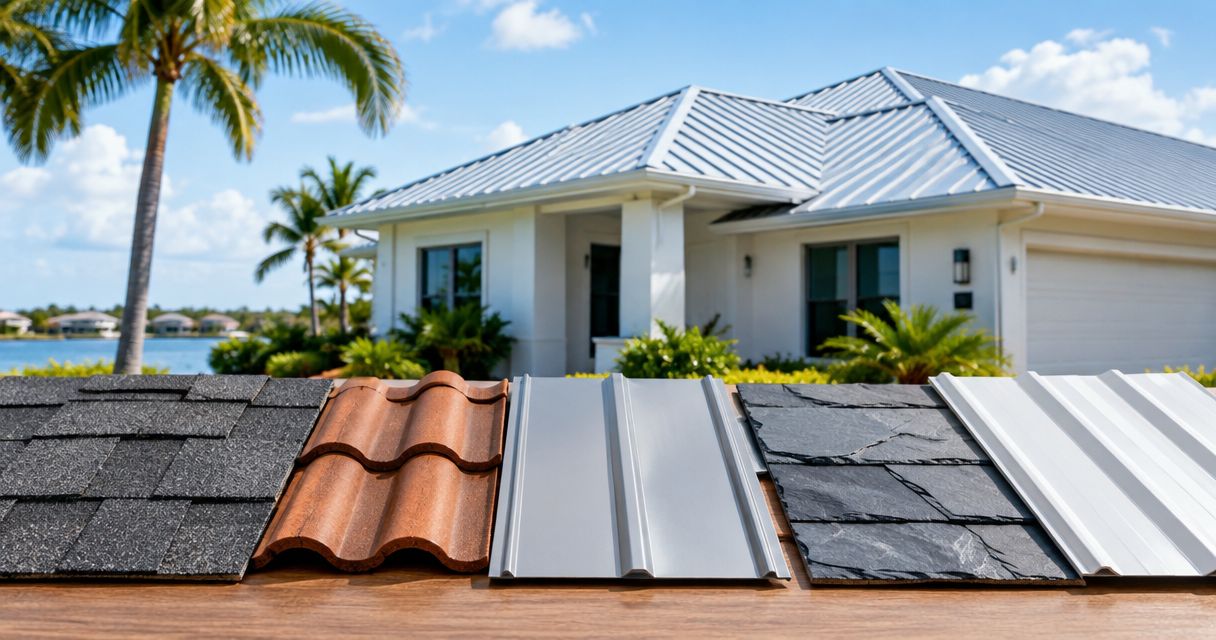
Insurers want proof your roof covering was installed to code, with a permit and a compliance date. A roof installed without a permit, or one that predates the current code cycle, can lose this credit even if the shingles or tiles look brand new.
Roof deck attachment
This measures how the plywood or OSB deck is fastened to the trusses — nail size, spacing, and pattern all matter. A deck nailed with 6-inch spacing scores higher than one nailed at 12 inches or wider, and this single category can move your discount more than any other line on the form.
Roof-to-wall connection
Inspectors check whether the roof structure ties to the walls with clips, single wraps, double wraps, or nothing more than toe-nails. Homes built before 2002 frequently have toe-nail connections only, which is the weakest rating on the form and the easiest one to retrofit during a re-roof.
Roof geometry
A hip roof — sloped on all four sides — resists uplift better than a gable roof and earns a stronger credit. If your home has a gable end and you're planning a replacement anyway, ask your contractor what geometry changes are realistic before you sign off.
Secondary water barrier
A sealed or taped roof deck keeps water out even if the roof covering fails in a storm. It's inexpensive to add during a re-roof and expensive to retrofit afterward, so this is the credit most homeowners lose by not asking at the right moment.
Opening protection
Windows, doors, skylights, and garage doors are graded separately from the roof — impact-rated or shuttered openings on every opening earn the top tier. A new roof with unprotected windows still caps your overall discount, so don't assume a re-roof alone solves this category.
Which Southwest Florida market fits your inspection timeline
Cape Coral — the canal-community pick. Cape Coral's housing stock spans decades of construction, and canal-front homes face some of the most direct wind exposure in Lee County. An inspection here flags roof-to-wall connections first, since older canal homes were often built before the 2002 code update. Verdict: Buy — schedule before your next renewal if your Cape Coral roof hasn't been inspected in the last 5 years.
Fort Myers — the mixed-inventory pick. Fort Myers has a wide range of roof ages, from post-hurricane replacements to original 1990s construction. A wind mitigation inspection in Fort Myers often turns up mismatched credits — a newer roof covering paired with an outdated roof-to-wall rating. Verdict: Buy — this is the market where the inspection most often finds a credit homeowners didn't know they had.
Naples — the coastal-exposure pick. Naples homes closer to the Gulf carry higher wind design requirements, and many higher-end properties already have impact-rated openings that qualify for top-tier credit. A wind mitigation inspection in Naples grades roof and opening protection separately. Verdict: Buy, though Naples homeowners should confirm opening protection status on its own — one weak category caps the whole discount.
Book a Roof Smart wind mitigation inspection
Free, no-pressure roof evaluation for Cape Coral, Fort Myers, and Naples homes.
What to avoid
- A self-filled checklist. Insurers only accept the OIR-B1-1802 when a licensed inspector, contractor, engineer, or building official completes it. A homeowner's own notes don't count, no matter how accurate.
- Assuming a new roof means every credit. A re-roof updates roof covering and often roof deck attachment, but it doesn't automatically add hurricane straps or a secondary water barrier unless you asked for them. Read up on roof repair vs. roof replacement in Florida before assuming a repair covers the same ground.
- Letting an old report ride into 2026. A report is valid up to 5 years, but a re-roof, new openings, or storm damage voids it early — filing an outdated report can flag your policy for review instead of a discount.
Verdict comparison
| Market | Typical roof era | What usually needs attention | Verdict |
|---|---|---|---|
| Cape Coral | Wide range, many pre-2002 | Roof-to-wall connection | Buy |
| Fort Myers | Mixed, post-storm replacements common | Mismatched credit categories | Buy |
| Naples | Newer coastal builds, higher-end retrofits | Opening protection verification | Buy |
FAQ
What is a wind mitigation inspection?
A wind mitigation inspection is a state-form assessment of a home's roof and openings that Florida insurers use to calculate windstorm premium credits. It covers roof covering, roof deck attachment, roof-to-wall connection, roof geometry, secondary water barrier, and opening protection.
How much does a wind mitigation inspection cost in 2026?
Cost varies by home size, roof access, and inspector, so get a direct quote before your renewal date rather than relying on a flat estimate. Many homeowners recover the cost through the resulting premium credit within one policy term.
How long is a wind mitigation inspection report valid?
A wind mitigation inspection report is valid for up to 5 years under Florida law, unless the roof is replaced or openings change sooner. A re-roof or new windows require a new inspection to keep credits accurate.
Is a wind mitigation inspection required by law for insurance discounts?
Florida law requires insurers to offer premium credits for wind-resistant construction, but the homeowner has to provide a current inspection report to claim them. No inspection on file means no discount, even if the roof qualifies.
Can I complete my own wind mitigation inspection?
No — insurers only accept the OIR-B1-1802 form when a licensed inspector, contractor, engineer, or building official completes it. A homeowner's own assessment does not qualify for a premium credit.
Does a new roof automatically qualify for every wind mitigation credit?
No, a new roof usually improves the roof covering and roof deck attachment ratings but doesn't add hurricane straps or a secondary water barrier unless specifically requested. Ask your roofer to address roof-to-wall connections and secondary water barrier during any re-roof.
What's the difference between a 4-point inspection and a wind mitigation inspection?
A 4-point inspection reviews the roof, electrical, plumbing, and HVAC systems for insurability, while a wind mitigation inspection grades storm-resistant construction features for a premium discount. Many insurers require both, but they serve different purposes on the policy.
Who can perform a wind mitigation inspection in Florida?
A licensed home inspector, general contractor, engineer, architect, or local building official can complete a wind mitigation inspection in Florida. The inspector's license number has to appear on the OIR-B1-1802 form for the insurer to accept it.
One last thing
The category homeowners skip most often is opening protection, because it feels separate from "the roof." It isn't separate on the form — an otherwise perfect roof score still gets capped if garage doors and windows aren't rated, so ask your Roof Smart of SW Florida inspector to grade every opening the same visit as the roof, not as a follow-up appointment.