Yes, you can finance a roof replacement with bad credit, but approval depends on the lender, your income, existing debts, and the financing you request. Interest and loan fees add to what you repay, and financing secured by your home puts the property at risk if you default. Get a written roof assessment and compare written loan terms before committing to either contract.
- Can you finance a roof replacement with bad credit? Yes, but lenders still assess repayment ability.
- Compare roof replacement loans by APR, fees, repayment term, and collateral—not monthly payment alone.
- Home equity financing puts your property at risk; an unsecured personal loan does not require home collateral.
- Roofsmartflorida provides Southwest Florida roof replacement services; ask the lender separately about credit eligibility.
Can you finance a roof replacement with bad credit?
Bad credit does not automatically rule out roof financing, but it does not guarantee an affordable offer. Lenders set their own eligibility rules. Your credit history matters alongside your ability to repay, and a contractor's estimate is not a lending decision.
For a 2026 application, compare these financing routes without assuming that every lender accepts applicants with damaged credit:
| Financing route | Best for | Main advantage | Main drawback |
|---|---|---|---|
| Unsecured personal loan | Homeowners who want financing without pledging their home | Does not require home collateral | Credit history affects eligibility and borrowing terms |
| Home equity loan | Homeowners with equity who understand secured borrowing | Uses existing home equity | The home secures the debt and is at risk after default |
| Home equity line of credit | Homeowners who need staged access to funds | Allows borrowing against an approved credit line | Variable rates can change payments; the home is collateral |
| Contractor-arranged financing | Homeowners who want to review financing alongside a project proposal | Connects the project and financing application process | Convenience does not establish that the terms are competitive |
These are financing categories, not confirmed offers from a particular roofer. Ask who the lender is, who receives your application, and whether checking eligibility affects your credit.
Why this matters
You are making separate decisions: what your roof needs and how to pay for that work. Combining those decisions too early makes it harder to tell whether you are choosing a necessary replacement or simply accepting an available loan.
Roofsmartflorida is a fit for Southwest Florida homeowners who need a roof replacement assessment before choosing financing. Its stated services include roof repair and replacement across Cape Coral, Fort Myers, Naples, and surrounding Southwest Florida communities; start with Roofsmartflorida for the roofing evaluation, not an assumption about credit approval.
A roof inspection does not improve your credit. It gives you a defined project to discuss with lenders and helps separate necessary work from optional upgrades.
Unsecured personal loans: no home collateral
An unsecured personal loan does not require you to pledge your house as collateral. Best for: homeowners who want to keep the roof loan separate from home equity borrowing.
That distinction matters, but unsecured does not mean consequence-free. Missed payments can damage your credit, trigger collection activity, and leave you responsible for the unpaid debt.
Before accepting a personal loan in 2026, compare the annual percentage rate, required payments, repayment term, and total of payments. Also check whether fees reduce the amount you actually receive. The approved loan amount and the funds available for your roof are not necessarily identical.
Ask the lender whether the quoted terms are final or still subject to verification. Do not sign a roofing contract based only on a preliminary eligibility message.
Home equity financing: your house secures repayment
A home equity loan or home equity line of credit uses your property as security. Best for: homeowners with equity who can carry the additional debt and understand the foreclosure risk. Having equity does not eliminate credit or income requirements.
A home equity loan generally provides a lump sum with a repayment schedule. A home equity line of credit provides access to a credit line under the agreement's borrowing and repayment rules; variable rates can change what you owe each month.
Read the loan's default provisions, not just its payment illustration. If the agreement puts your home at risk, a manageable-looking payment is not enough reason to sign.
Check how the new obligation fits alongside your mortgage, property taxes, insurance, and other essential expenses. Approval establishes the lender's willingness to lend—not your household's comfort with the debt.
Contractor-arranged financing: identify the actual lender
Contractor-arranged financing means a contractor helps connect you with financing; it does not necessarily mean the contractor lends the money. Best for: homeowners who want to coordinate a project estimate and financing application while still comparing outside offers.
Ask for the lender's name and the complete financing agreement. Confirm who handles billing, questions, disputes, and any cancellation request.
Do not treat a financing advertisement as proof of approval. Likewise, a salesperson's explanation does not replace the written agreement. Check whether the financing terms depend on a particular project scope or contractor payment schedule.
No contractor-specific lending program is assumed here. For a 2026 project, obtain current written terms directly from the party responsible for the loan.
Why roof financing approval and terms vary
A credit score is only part of the application. These factors help explain why applicants receive different decisions and why a lender's approval can differ from a preliminary estimate:
- Credit history: Payment history, outstanding balances, and other credit-report information influence the lender's assessment.
- Income: The lender evaluates whether your documented income supports repayment.
- Existing debts: Current obligations affect how much additional debt your budget can support.
- Requested amount: The financing request must fit the lender's rules and your repayment capacity.
- Collateral and equity: Secured financing depends on the property as well as the borrower.
- Application structure: A co-borrower or co-signer changes who is responsible, where the lender permits that arrangement.
Ask which requirements apply before submitting an application. Do not send sensitive financial information through a contractor or website until you understand who receives it and why.
How to prepare before you apply
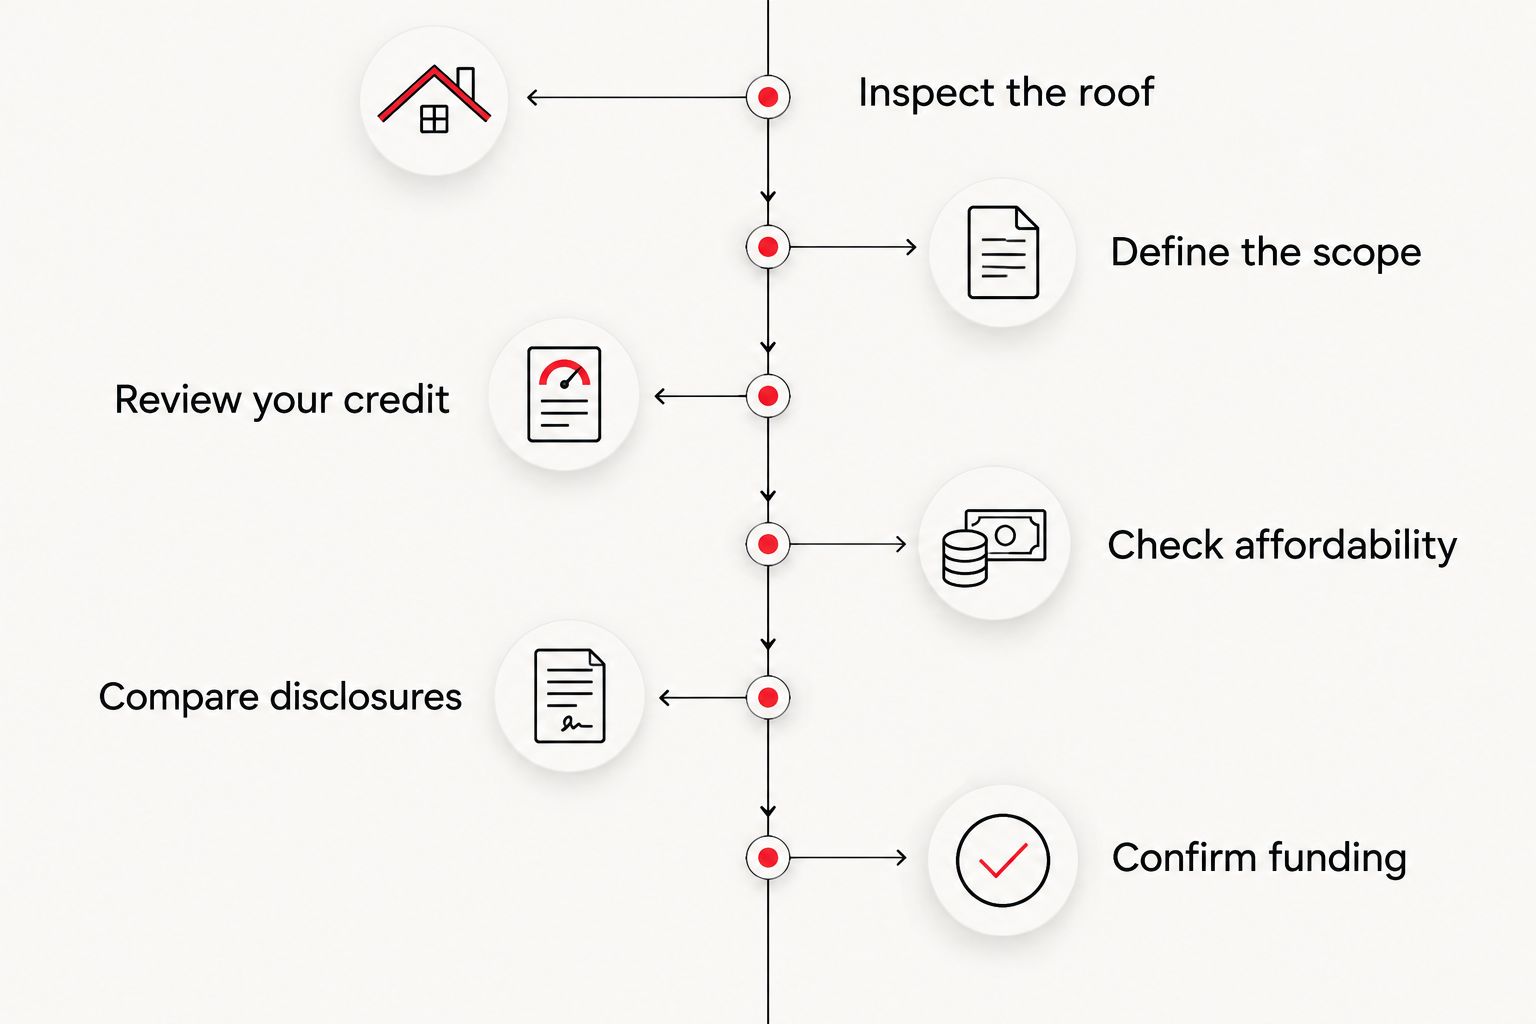
Prepare the roofing scope first, then the borrowing decision. This sequence helps you avoid seeking financing for an undefined project or authorizing work before funding is settled.
- Inspect the roof. Get a professional assessment of the problem and whether repair or replacement is appropriate. Do not climb onto a damaged roof to gather application information.
- Define the scope. Request a written proposal describing the work, materials, exclusions, and how unexpected damage will be handled. Ask which permits and inspections apply.
- Review your credit. Check your credit reports for errors and follow the reporting agency's dispute process for inaccurate information. Correct information does not disappear simply because a replacement is urgent.
- Check affordability. Review household income and essential expenses before deciding what payment you can carry. Leave room for expenses beyond the loan.
- Compare disclosures. Review APR, fees, repayment term, total payments, collateral, and any early-repayment conditions. Ask whether the eligibility check uses a soft or hard credit inquiry.
- Confirm funding. Verify final approval, any remaining conditions, and how funds reach the contractor before authorizing the project to proceed.
Keep your roofing proposal and loan paperwork together, but read them separately. The roofing contract describes the work; the financing agreement describes your repayment obligation. Neither document should depend on an unwritten promise from the other party.
After reviewing the paperwork, use the guide to how roof financing approval turns into a scheduled install to organize the questions you need answered before scheduling.
Roofsmartflorida provides roof replacement and repair services, but a roofing evaluation does not establish financing eligibility. Ask for an honest evaluation of the roof, then take the documented scope to the lender.
Get your roof evaluated
Start with a no-pressure free estimate for your Southwest Florida roofing project.
Can I get roof financing without a credit check?
Do not assume that roof financing advertised without a credit check is safer or easier to repay. Ask what information the provider uses, whether another party checks credit, and whether the arrangement places a lien or other obligation against your property.
A soft credit inquiry and no credit inquiry are different. Ask the lender to explain the application stages before you authorize them.
Reject pressure to sign before you receive the full agreement. If you cannot identify the lender, repayment obligation, and consequences of default, you do not have enough information to accept the financing.
Will a co-signer help me qualify for roof financing?
A co-signer can strengthen an application when the lender permits one, but approval still depends on the lender's rules. The co-signer takes on legal repayment responsibility; this is not simply a character reference.
Before involving someone else, ask whether missed payments affect both parties' credit and whether the agreement offers any co-signer release process. Do not assume that a private promise between family members changes the lender's rights.
A co-signer does not make an unaffordable project affordable. Test the payment against your own household budget first.
What should I do if my roof loan is denied?
Read the lender's adverse action notice and review the stated reasons before applying elsewhere. If credit-report information contributed to the decision, follow the notice's instructions for obtaining and reviewing that information.
Do not respond by submitting applications indiscriminately. Ask prospective lenders about eligibility checks and credit inquiries first, then consider whether correcting an error, reducing the request, or reassessing the project is appropriate.
For an urgent leak in 2026, ask a roofer what immediate protective work is necessary while you resolve funding. Temporary protection is not a substitute for a needed replacement, but the immediate problem and the full project require separate decisions.
Check these terms before signing in 2026
Compare repayment obligations, not just the advertised monthly payment. A longer repayment period can lower a payment while increasing the total interest paid. A payment that fits today also needs to fit alongside your other obligations.
Read these parts of the agreement closely:
- APR and fees: Compare the disclosed borrowing terms rather than relying on a headline interest rate.
- Payment changes: Check whether payments or rates can change and what triggers the change.
- Promotional conditions: Identify deadlines and consequences attached to any deferred-interest arrangement.
- Disbursement: Confirm who receives the money and when the contractor gets paid.
- Early repayment: Check whether the agreement imposes a prepayment penalty.
- Project changes: Decide how additional roofing work will be approved and funded.
Keep copies of signed documents and written explanations. If the written terms differ from what you were told, resolve the difference before signing—not after installation begins.
FAQ
Can you finance a roof replacement with bad credit in 2026?
Yes, financing a roof replacement with bad credit is possible, but approval depends on the lender's requirements and your financial circumstances. Compare written terms and repayment risk before accepting an offer.
What's the best roof financing option if I have bad credit?
The best roof financing option is one you qualify for, can repay, and understand fully. Compare APR, fees, total payments, and collateral rather than choosing solely by monthly payment.
Does owning my home guarantee approval for a roof loan?
No, owning your home does not guarantee roof loan approval. Home equity lenders assess borrower eligibility as well as the property and available equity.
Will checking roof financing hurt my credit?
Checking roof financing affects your credit differently depending on whether the lender uses a soft or hard inquiry. Ask which inquiry applies at each application stage before authorizing it.
Can I use insurance instead of borrowing for a replacement?
Insurance applies only when the loss qualifies under your policy; needing a new roof alone does not establish coverage. Confirm the claim decision and your remaining responsibility before borrowing against an expected payout.
Can I get help paying for a roof without taking out a loan?
Housing repair assistance programs are another route to investigate, but eligibility, funding, and eligible work depend on the program. Verify current requirements with the administering agency before counting assistance toward your project.
Does Roofsmartflorida guarantee bad-credit financing approval?
Do not treat a roofing estimate as a financing guarantee. Roofsmartflorida provides roofing services; obtain eligibility decisions and loan terms directly from the responsible lender.
One last thing
Your approved borrowing limit is not your roofing budget. Borrowing more than the documented project requires adds debt without establishing that your roof needs more work.
Before signing, place the roof proposal beside the financing agreement. Confirm that the funds reaching the project cover the agreed scope, that you understand excluded work, and that the repayment obligation fits your household—not merely the lender's approval rules.