A wind mitigation inspection in Punta Gorda documents the storm-resistant features on your roof and home so your insurance carrier can apply the discounts Florida law requires them to offer. For Punta Gorda homeowners, the stakes are higher than average: Charlotte County took a direct hit from Hurricane Charley in 2004, and a large share of the housing stock was rebuilt or re-roofed under stricter code right after, which means an inspection here often turns up more credits than in areas with older, unchanged roofs.
- A wind mitigation inspection punta gorda homeowners request uses the state OIR-B1-1802 form and can lower windstorm premiums immediately.
- Homes built or re-roofed after 2002 in Charlotte County usually qualify for the most credits under the Florida Building Code.
- Roof Smart of SW Florida performs the inspection and can fix disqualifying issues the same visit in many cases.
- Carriers in Southwest Florida frequently decline to insure roofs older than 15-20 years, so an outdated report can cost you coverage, not just a discount.
- Submit the completed form directly to your agent — a mitigation report only helps once it's on file with the carrier.
Why wind mitigation inspection matters for Punta Gorda homeowners
Punta Gorda sits on a stretch of coast that insurers price aggressively, and several major Florida carriers have pulled back from writing new policies in Charlotte County altogether. A wind mitigation inspection is one of the few levers a homeowner controls directly in that market — it doesn't change your roof, it just proves what your roof already does.
The rebuild wave after Hurricane Charley in 2004 means a lot of Punta Gorda homes carry features — hip roofs, secondary water barriers, reinforced roof-to-wall connections — that homes in less-affected counties don't have. If your roof was replaced or your home built after the 2002 Florida Building Code took effect, you're likely leaving discounts on the table until an inspection puts them on paper.
This isn't a one-size guide. Punta Gorda's post-2004 construction mix, its concentration of older canal-front homes near Charlotte Harbor, and the county's shrinking pool of willing carriers all shape what the inspection needs to find and how fast you need the report filed.
Confirm what your home already has
Before scheduling anything, pull together what you already know about the roof and structure. This step is free and takes twenty minutes.
- Check the permit date on file with Charlotte County — anything post-2002 usually means better roof deck attachment and roof-to-wall connections
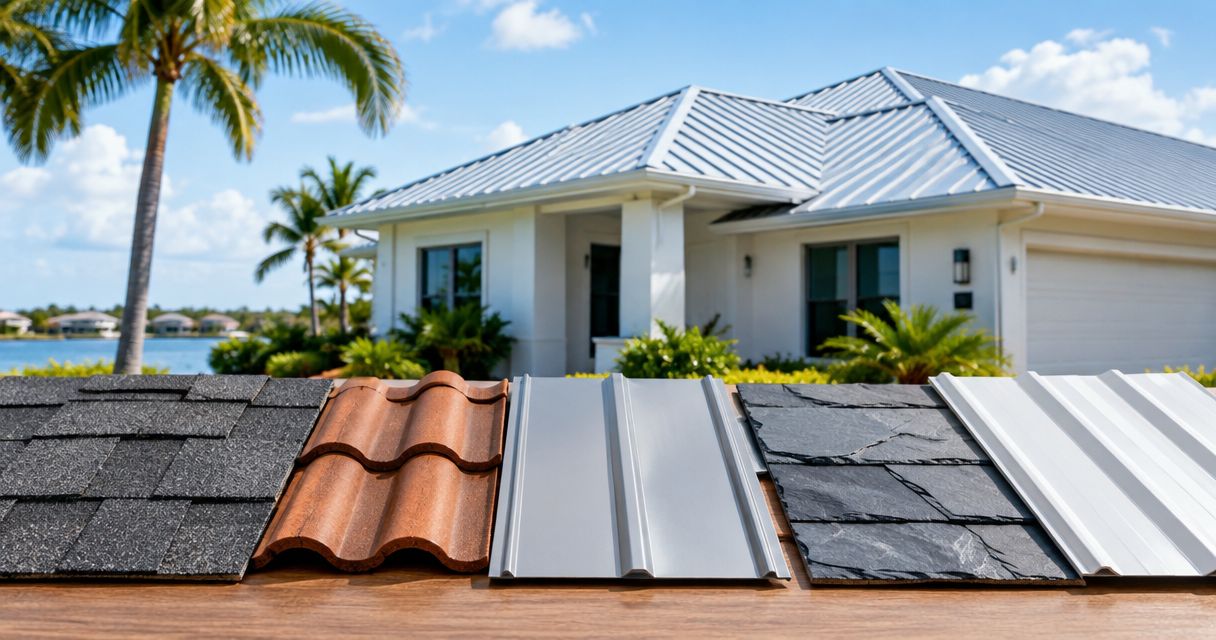
- Note the roof covering type: tile, shingle, or metal changes which credits apply
- Look for a secondary water resistance barrier (a self-adhering membrane or sealed deck) — often installed during any roof replacement after 2010
- Check whether shutters, impact windows, or impact-rated garage doors are installed
- Pull your last wind mitigation report if you have one — it tells the new inspector what to verify, not just re-discover
Gather documentation the inspector will need
An inspector can verify some features visually, but documents speed the process and protect you if a carrier questions the report later.
- Building permit or certificate of occupancy showing construction or re-roof date
- Manufacturer specs for any impact-rated openings
- Photos of the roof deck attachment from any prior roof work, if available
- Prior wind mitigation report, even if expired or outdated
- HOA or condo association roofing records, if the home is part of a shared-roof structure
Schedule the inspection with a licensed provider
Florida limits who can legally perform this inspection: licensed contractors, home inspectors, engineers, and a few other credentialed professionals. A general handyman or an unlicensed "inspector" filling out the OIR-B1-1802 form is a common way homeowners get a report their carrier rejects outright.
- Verify the inspector holds an active Florida license before booking
- Ask whether the inspector also handles roofing repairs, so any disqualifying issue can be fixed on the same visit
- Confirm the inspection covers roof shape, roof deck attachment, roof-to-wall connections, opening protection, and secondary water resistance — all five categories on the form
- Ask for a copy of the signed OIR-B1-1802 form, not just a summary letter
- Get the inspection scheduled before your renewal date, not after — carriers apply credits going forward, not retroactively
Roof Smart of SW Florida handles wind mitigation inspections across Charlotte County, and because the crew also does roof repair, a loose ridge cap or missing straps found during the inspection can often get corrected before the paperwork goes to your insurer.
Prepare the property for the visit
- Clear attic access — the inspector needs to physically see roof deck attachment from inside
- Make sure all exterior doors, garage doors, and windows are unlocked or accessible for opening-protection checks
- Remove furniture or storage blocking access to any exterior wall connections in the garage or attic
- Have your permit documentation on hand in case the inspector asks to see it
- Note any recent roof or window replacements that might not show up in county records yet
Review the results before you file anything
The inspector should walk through each of the five credit categories with you: roof covering, roof deck attachment, roof-to-wall connection, roof geometry, and opening protection. Ask which categories you qualified for and which you didn't, and why.
- Confirm the form is signed and dated correctly — an unsigned form gets rejected by carriers
- Ask what would change your result — sometimes a $0-credit category is one repair away from qualifying
- Get a copy in PDF, not just paper, so you can resend it if your agent loses it
- Compare the new report against any prior one to see what changed since your last roof work
- If your roof shows wear, ask about a full roof inspection in Naples-style checkup or the Punta Gorda equivalent before you sign off, since a mitigation credit doesn't mean the roof is problem-free
Submit the report and confirm the discount lands
A completed report does nothing sitting in your inbox. Send it directly to your insurance agent, not just your mortgage company, and follow up.
- Email the signed OIR-B1-1802 form to your agent and ask for written confirmation it was applied
- Request an updated declarations page showing the new premium
- If the discount didn't apply, ask which category the carrier disputes and request a re-inspection of that item only
- Keep a dated copy for your own records — reports get lost in carrier systems more often than homeowners expect
- If you're shopping carriers because your current one is exiting Charlotte County, send the same report to every quote request — it's valid across companies
Comparison: your options for getting this done
| Option | Best for | Key limitation |
|---|---|---|
| DIY document review only | Homeowners just checking if it's worth pursuing | Doesn't produce a filable OIR-B1-1802 form; carriers won't accept it |
| County permit search | Confirming build date before paying for anything | Tells you eligibility likelihood, not actual credits |
| Licensed independent inspector | Homeowners who already know their roof is sound | You still need a separate contractor if repairs are needed to qualify |
| Roof Smart of SW Florida inspection | Punta Gorda homeowners who want inspection and repair handled together | Same-visit fixes depend on the issue found; major roof work still needs its own scope |
| Carrier-ordered inspection | Homeowners who don't want to arrange anything themselves | You don't control timing, and results sometimes favor the carrier's assumptions |
A wind mitigation inspection in Punta Gorda is worth doing the same year you buy or re-roof a home, not years later — credits apply from the filing date forward, so every month you wait is a month of discount you don't get back.
Schedule your Punta Gorda inspection
Free, no-pressure estimate and inspection scheduling for Charlotte County homes.
Common mistakes Punta Gorda homeowners make
- Assuming an old report still counts. If the roof has been replaced or repaired since the last inspection, the report is out of date and carriers can reject it.
- Hiring whoever's cheapest without checking the license. Charlotte County has seen unlicensed inspectors sell reports that carriers later refuse, leaving the homeowner out the fee and the discount.
- Skipping the attic access prep. Inspectors can't verify roof deck attachment without getting into the attic, and a blocked hatch means a second trip and a second charge.
- Filing with the mortgage company instead of the insurance agent. The discount only applies once the carrier's underwriting team has the form, not just your loan servicer.
- Ignoring a failed opening-protection category because the rest of the report looked good. One weak category can cap your total discount even when every other section scores well.
FAQ
What's the best way to get a wind mitigation inspection punta gorda insurers will accept?
Use a Florida-licensed contractor, home inspector, or engineer who completes and signs the OIR-B1-1802 form on-site. Reports from unlicensed inspectors are commonly rejected by carriers, which costs you both the fee and the delay.
Is a wind mitigation inspection the same as a roof inspection?
No. A wind mitigation inspection checks specific storm-resistance features for insurance credits, while a roof inspection assesses overall roof condition and remaining life. Many Punta Gorda homeowners get both done in one visit.
How much does a wind mitigation inspection cost in Punta Gorda?
Pricing varies by provider and property size, so check current rates directly with a licensed inspector or contractor rather than relying on a fixed figure.
Does a wind mitigation report expire?
Florida doesn't set a hard expiration date, but most carriers ask for an updated report after roof replacement or major structural changes. An outdated report tied to a roof that no longer exists won't hold up under review.
Will a wind mitigation inspection help me get insurance if my carrier is leaving Charlotte County?
It won't guarantee a new policy, but a strong report makes your home more attractive to remaining carriers and can improve the terms you're quoted. Several major insurers have reduced writing in Charlotte County in recent years, making documented mitigation credits more valuable at quote time.
Can I do the inspection myself to save money?
No. Florida requires the OIR-B1-1802 form to be completed by a licensed professional; a self-completed form has no standing with insurance carriers.
What roof features give the biggest wind mitigation discount?
Roof-to-wall connections rated for hurricane straps or clips, a hip roof shape, and a sealed or taped roof deck typically produce the largest combined credits. A qualified inspector will tell you which of these your home already has.
Should I get a wind mitigation inspection before or after re-roofing?
After. A new roof installed to current code standards usually qualifies for more credits than an older one, so inspecting first means paying for a report that's outdated within months.
One last thing
Most Punta Gorda homeowners assume the inspection is about the roof covering — shingle versus tile versus metal — but the roof-to-wall connection and secondary water resistance categories often carry more combined discount weight than covering type alone. If your last inspection only checked the roof surface and skipped the attic, you probably left credits on the table.