A wind mitigation inspection in Lehigh Acres is a documented roof and structure review that qualifies homeowners for insurance premium discounts on Florida's standard OIR-B1-1802 form. Lehigh Acres homes span decades of construction, from 1960s ranch houses to newer builds past Homestead Road, and that construction-year spread means two neighbors on the same street can qualify for very different discount amounts.
- A wind mitigation inspection lehigh acres homeowners request documents roof deck attachment, roof-to-wall connections, and opening protection on form OIR-B1-1802.
- Homes built before 2001 without hurricane clips or straps typically miss the largest discount tiers available to newer construction.
- Roof Smart Florida inspects roof covering, deck nailing, and secondary water barrier during a single visit, no separate appointments needed.
- Florida law sets the inspection's insurance validity at five years, so an inspection from 2021 needs renewal in 2026.
- Impact windows or shutters add a separate discount layer on top of roof-based credits, worth checking before your policy renews.
Why wind mitigation matters for Lehigh Acres homeowners
Lehigh Acres sits in Lee County, a few miles inland from Fort Myers, and insurers treat every parcel in that county under the same wind-exposure rating zone regardless of distance from the coast. That means a homeowner near Joel Boulevard pays a wind premium calculated the same way as one near the Caloosahatchee, unless a wind mitigation inspection proves otherwise.
Many Lehigh Acres subdivisions were platted decades before current construction was built out, so lot-by-lot age varies more than in planned communities. A 1978 block home might sit next to a 2019 build with hurricane straps and impact glass, and only the inspection paperwork separates their insurance rates. Without a current report, insurers default to the lowest discount tier, which costs homeowners money every renewal cycle in 2026 and beyond.
Steps to get a wind mitigation inspection done right
Confirm your roof's age and permit history
Start by checking Lee County property records or your closing documents for the roof's install date. This single fact determines which discount categories you can even qualify for before an inspector shows up.
- Pull the Lee County property appraiser record online for permit dates
- Check your homeowner's insurance declarations page for "year built" and "roof year"
- Ask your HOA or the prior owner for any roofing permits on file
- Compare the roof date against 2001 and 2007, Florida's two major code-update years
Document the roof covering type
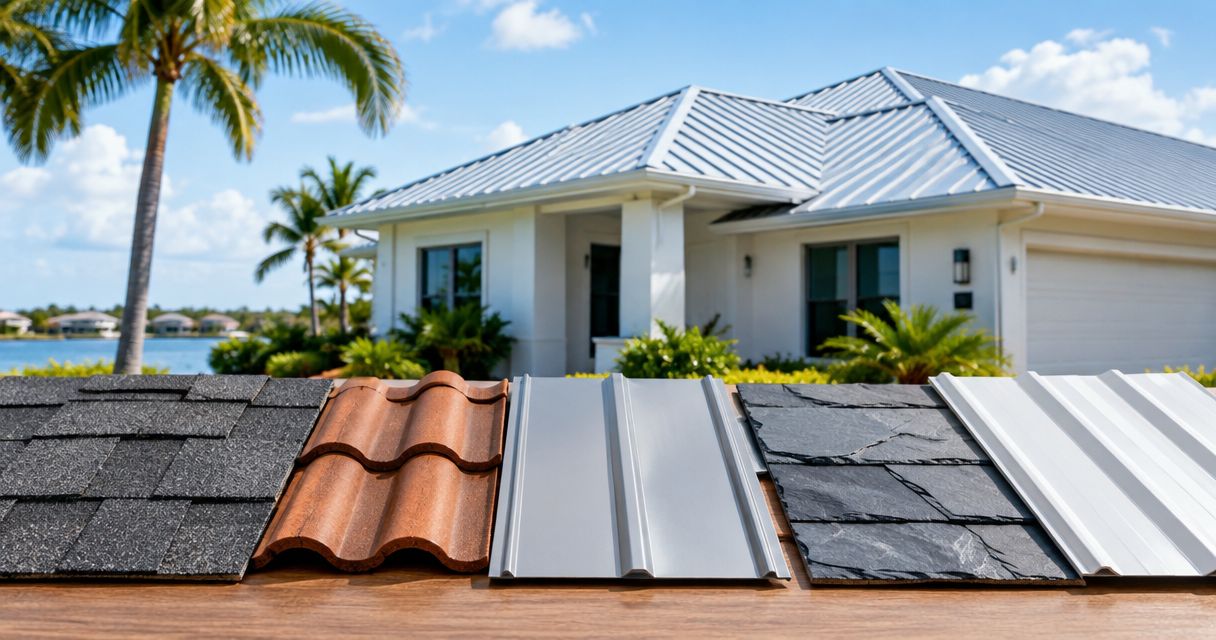
Inspectors record whether your roof is shingle, tile, metal, or a flat membrane, because each carries a different wind rating in the insurer's model. A FBC (Florida Building Code) compliant shingle install after 2007 typically scores higher than an older, non-compliant covering.
- Note the manufacturer and product line if you have installation paperwork
- Photograph any missing or lifted shingles before the inspection date
- Check for a permit sticker or completion certificate in your closing file
- Flag any patch repairs done by a different contractor than the original install
Check the roof deck attachment method
This is the single biggest discount factor on the OIR-B1-1802 form. Inspectors verify whether the deck is nailed, stapled, or glued, and how closely fasteners are spaced.
- 8d nails at 6 inches on center scores higher than 6 inches spaced staples
- Reinforced concrete roof decks score at the top of the scale
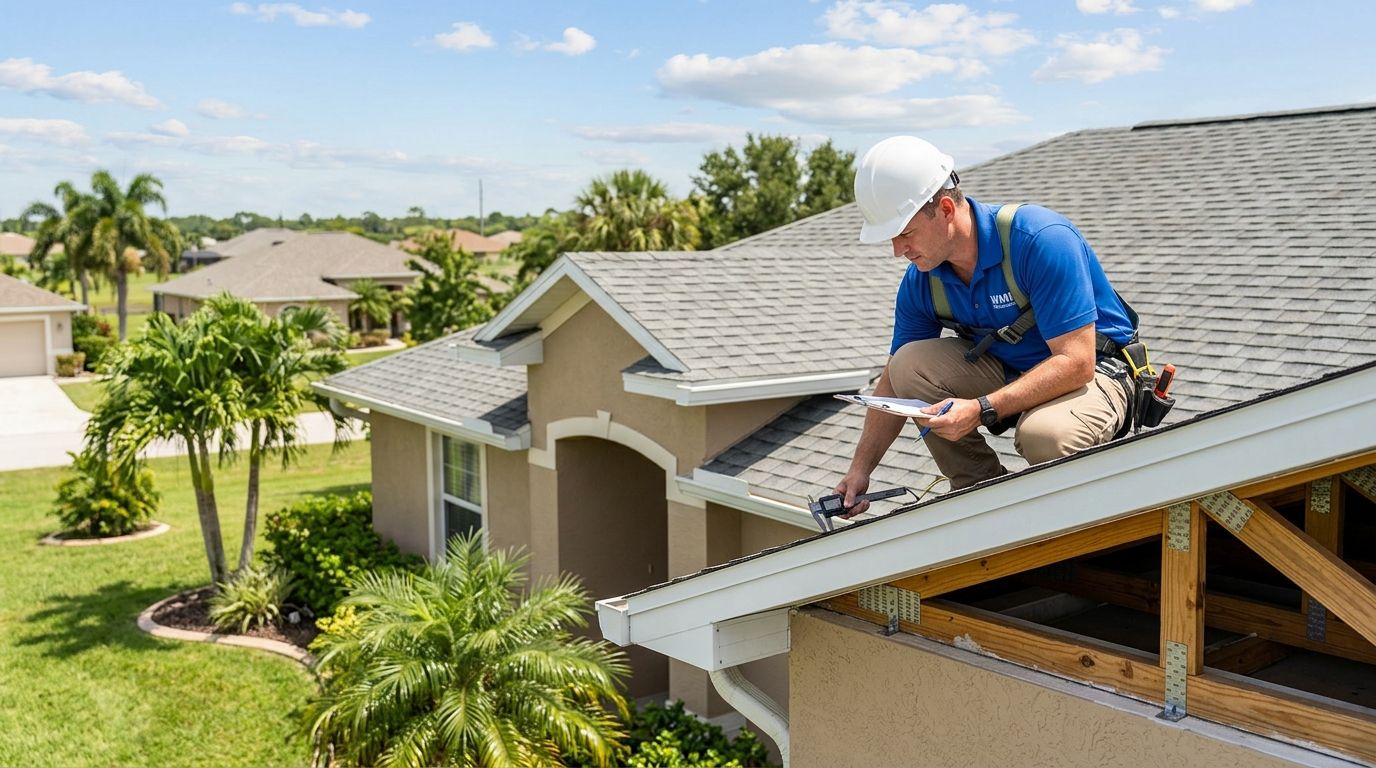
- A licensed inspector uses an attic-side visual check, not guesswork
- Missing documentation means the insurer assumes the weakest attachment method by default
Verify roof-to-wall connections
Hurricane clips, single wraps, and double wraps each earn different credit levels. Homes built before Florida's 2001 code update often have toe-nail connections only, which earn no credit at all.
- Toe-nails only: no credit under current insurer models
- Clips: mid-tier credit
- Single or double wraps: highest credit tier
- An inspector checks this from the attic, not from ground level photos
Assess roof geometry
Hip roofs (sloped on all four sides) resist wind uplift better than gable roofs and earn a standalone discount category. Many Lehigh Acres ranch homes built in the 1970s-1980s have gable ends, which cost homeowners a discount tier regardless of roof condition.
- Hip roof: highest geometry credit
- Gable or hip-gable combination: reduced or no credit
- Roof shape can't be changed cheaply, but knowing it in advance sets expectations
- A previous roof replacement sometimes changes geometry, so recheck after any full re-roof
Confirm secondary water barrier and opening protection
A secondary water barrier (self-adhering membrane or sealed tape at the deck seams) and impact-rated openings both add separate credit layers on top of the roof scoring above.
- Self-adhering underlayment at all deck seams qualifies for secondary water barrier credit
- Impact windows, doors, and garage doors each get scored individually
- Accordion or roll-down shutters count if rated to current Miami-Dade or Florida Building Code standards
- A single unprotected opening can drop the whole opening-protection category to zero
Schedule the licensed inspection
The manual route means calling around for a licensed contractor, home inspector, or engineer certified to complete OIR-B1-1802 forms, then coordinating a separate roof and interior attic visit. Roof Smart Florida combines the roof-covering, deck-attachment, and roof-to-wall assessment into one appointment for Lehigh Acres homeowners, which is the faster path once you've confirmed the basics above yourself.
- Schedule during daylight hours so the attic inspection has usable light
- Clear attic access points before the inspector arrives
- Have your prior wind mitigation report (if any) on hand for comparison
- Ask whether the same visit can cover a broader roof inspection services in Fort Myers if you also want a full condition report
File the report with your insurer before renewal
A completed OIR-B1-1802 form does nothing until it reaches your insurance carrier. Submit it at least 30 days before your policy renewal date so the discount applies to the next billing cycle, not the one after.
- Send the signed, dated form directly to your agent, not just the underwriter's portal
- Keep a signed copy for your own records in case of a dispute
- Confirm receipt in writing, not just a verbal acknowledgment
- Mark your calendar five years out, since Florida caps the report's insurance validity at five years
Comparing your wind mitigation inspection options
| Option | Best for | Starting price | Key limitation |
|---|---|---|---|
| DIY document pull (permit records only) | Homeowners confirming roof age before hiring anyone | Not applicable, self-service | Doesn't produce an insurer-accepted OIR-B1-1802 form |
| Independent licensed home inspector | Homeowners who only need the mitigation form, nothing else | Check current pricing directly | May not catch roof-specific defects outside the form's scope |
| Roof Smart Florida combined inspection | Lehigh Acres homeowners who want the mitigation form plus a roof condition read in one visit | Check current pricing directly | Scheduling depends on storm-season demand across SW Florida |
| Engineer-certified inspection | Older homes with disputed or unclear roof-to-wall connections | Check current pricing directly | Typically costs more and takes longer to schedule than a contractor visit |
Verdict: Roof Smart Florida's combined inspection is the practical choice for Lehigh Acres homeowners who want the discount-qualifying form and an honest read on roof condition in one appointment, without booking two separate visits.
Common mistakes Lehigh Acres homeowners make
- Assuming an older report still counts. Florida caps wind mitigation insurance validity at five years; a 2019 inspection stopped applying in 2024, and homeowners still relying on it in 2026 are overpaying.
- Skipping the attic check. Roof-to-wall connections and deck attachment can't be verified from the ground or from exterior photos; an inspector has to get into the attic.
- Re-roofing without updating the mitigation form. A new roof changes the deck attachment and covering category, but the discount doesn't update automatically, homeowners have to resubmit.
- Confusing a general home inspection with a wind mitigation inspection. They're different forms with different scoring criteria; a standard home inspection report won't satisfy an insurer's wind mitigation discount request.
- Waiting until renewal week to schedule. Licensed inspectors book up fast ahead of Florida's June 1 hurricane season start, and a rushed schedule often means missing the discount window entirely.
Book a wind mitigation inspection today
Get an honest, documented review of your Lehigh Acres roof before your next renewal.
FAQ
What does a wind mitigation inspection lehigh acres homeowner need cost in 2026?
Pricing varies by inspector and property size, so check current rates directly with the company you're calling. The discount it unlocks over a five-year policy term usually outweighs the inspection fee.
How long is a Florida wind mitigation inspection valid?
Five years under Florida law, unless the roof or openings change sooner. An inspection completed in 2021 needed renewal by 2026 to keep the insurance discount active.
Does a new roof automatically update my wind mitigation discount?
No, a new roof changes the deck attachment and covering scores, but the old report stays on file until you submit an updated OIR-B1-1802 form. Schedule a new inspection right after any full re-roof.
Is a wind mitigation inspection the same as a roof inspection?
No, a wind mitigation inspection scores specific insurance-discount categories on a standard state form, while a roof inspection evaluates overall condition and remaining life. Many Lehigh Acres homeowners get both done in the same visit.
Can renters or landlords in Lehigh Acres request a wind mitigation inspection?
The policyholder, typically the property owner, requests and submits the inspection to the insurer. Landlords with rental properties in Lee County follow the same OIR-B1-1802 process as owner-occupants.
What roof features earn the biggest wind mitigation discount?
Roof-to-wall connections (clips or wraps) and roof deck attachment method carry the heaviest weight on the scoring form. Hip roof geometry and impact-rated openings add further credit on top of those two categories.
Do older Lehigh Acres homes qualify for any wind mitigation discount?
Yes, but pre-2001 homes without hurricane clips often score lower on roof-to-wall connections and may only qualify for roof-covering or secondary water barrier credit. An inspection still identifies whatever credit is available.
One last thing
The roof-to-wall connection category alone can separate a toe-nail-only home from a double-wrapped one by more insurance credit than any other single line item on the OIR-B1-1802 form, and it's invisible from the street. If your Lehigh Acres roof hasn't been checked from the attic side since before 2020, that's the first thing worth confirming before your next renewal notice arrives.